Ireland's Central Statistics Office (CSO) figures, as reported by Tourism Ireland, show that the first quarter of 2026 — January through March — welcomed more than 1.3 million overseas visitors, 24% more than in the same period of 2025. Spend grew across every source market: North America up 26%, mainland Europe up 24%, Great Britain up 22%. The same release notes that Q1 typically accounts for around 13% of Ireland's annual overseas visitor spend, so strong growth in these months is meaningful but starts from a small seasonal base.
The trend did not stop in March. For January to June 2026, Tourism Ireland reports more than 3.2 million overseas visitors, 15% more than in the first half of 2025, and says this puts visitor numbers on par with 2024, which was a record year for visitor spend. For a group operator, a shift like this is not travel trivia. It is a signal about where shoulder-season demand may be heading, and it is worth weighing when deciding how early to contract Irish product.
What the shift may change for group contracting
Shoulder season in Ireland has traditionally meant softer demand and softer pricing on both accommodation and coach availability. If overseas visitor demand keeps growing in the months outside the summer peak, that gap could narrow: accommodation and ground-transport capacity that used to sit idle in January and February would be absorbed sooner, and some of the pricing advantage that made shoulder-season Irish programmes attractive would compress with it. This is an inference from the growth figures, not something the statistics measure directly, so it is worth checking against the availability of each programme.
The practical consequence is timing, not price alone. A shoulder-season Irish group programme can still offer better availability and room to negotiate than a July departure, but the window in which that advantage holds may be shorter than it used to be. Groups contracted early in the shoulder window are better placed to capture it. Groups contracted late may be competing with demand that used to arrive in summer.
The shoulder season has not necessarily disappeared as an advantage. It may have become a narrower one, and narrower windows tend to reward operators who contract early over operators who wait for a confirmed group size.
The one date that tends to break the pattern
One exception holds regardless of the broader shift: the week around St Patrick's Day. Dublin is typically one of the busiest places in Europe that week, accommodation rates rise, city-centre traffic restrictions around the parade route affect coach routing and drop-off points, and availability tightens well in advance. A group programme planned for mid-March should be contracted on a summer-style timeline rather than a shoulder-season one — and a programme with flexibility to shift a few days either side of the peak date can find noticeably better availability and rates without losing the occasion.
Where this leaves group demand outside Dublin
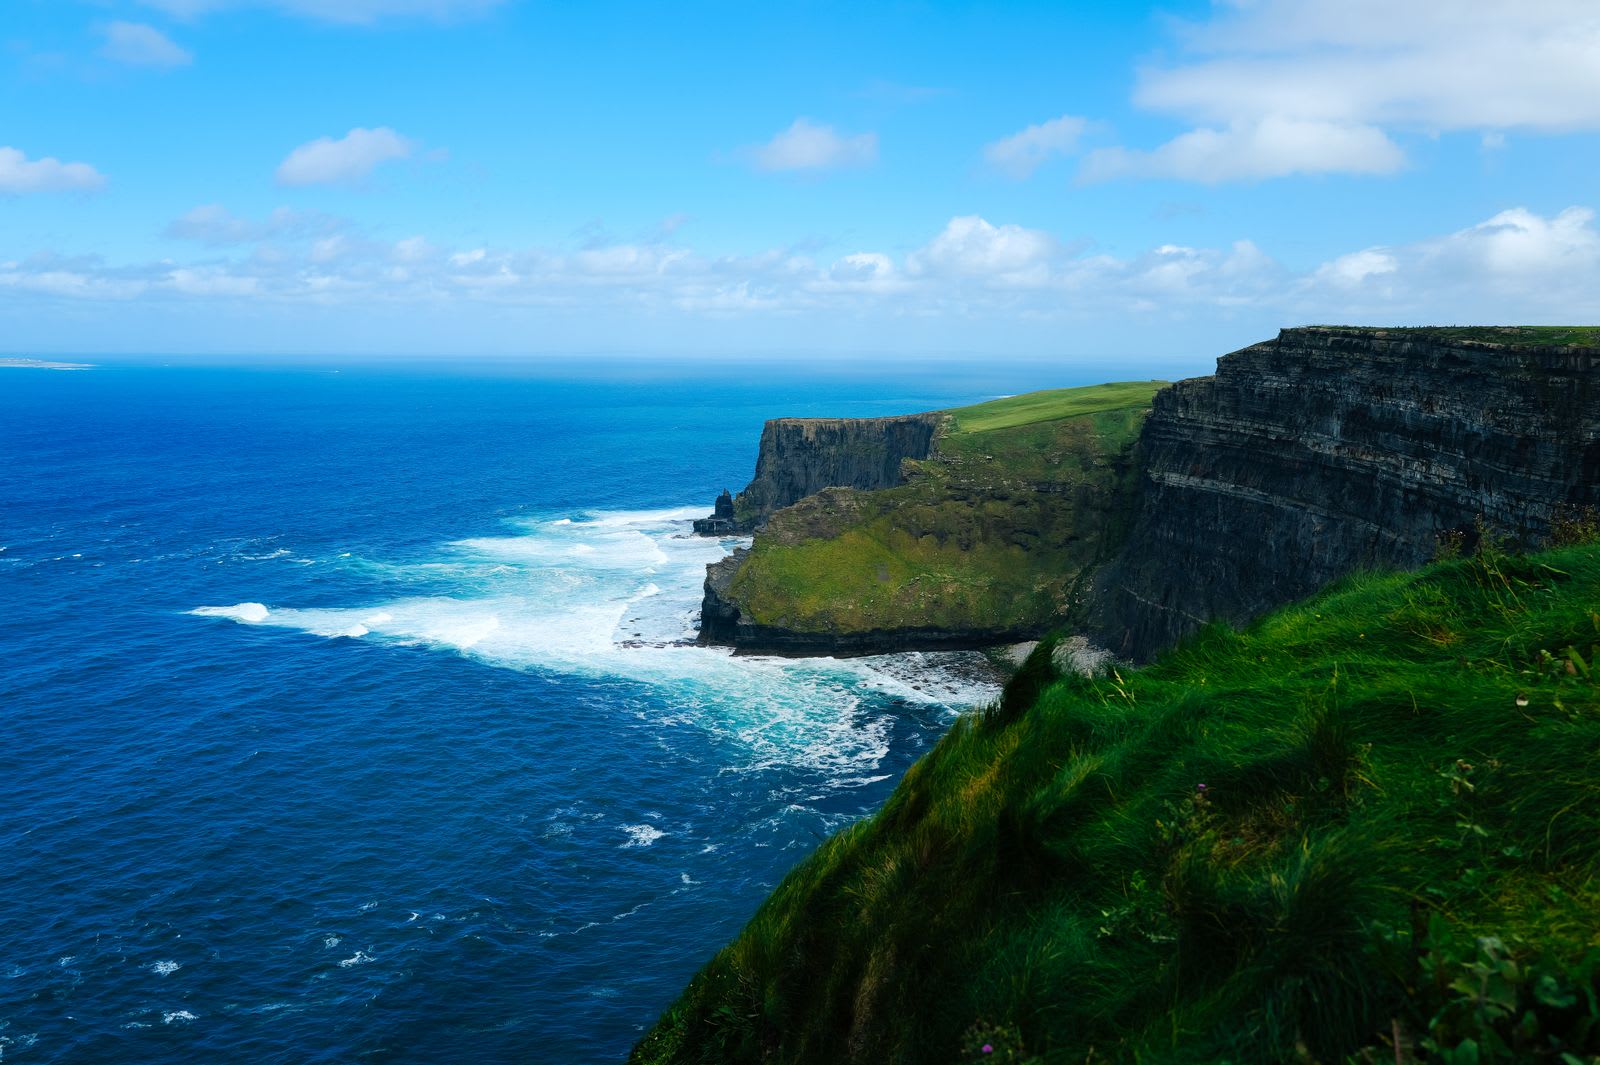
The CSO growth is national, not Dublin-specific, which matters for operators building multi-stop Irish itineraries. The west coast corridor — Galway, the Cliffs of Moher, Dingle and Kerry — tends to run on a different capacity rhythm than Dublin: a smaller accommodation stock, thinner coach supply on rural routes, and a tourism season that can contract further outside July and August than Dublin's does. A group itinerary built purely around Dublin is exposed to the national trend most directly. One that extends west needs its own contracting timeline for the accommodation and coach capacity outside the capital, which does not necessarily move in lockstep with Dublin's.
Frequently asked questions
Does Ireland's Q1 growth mean shoulder-season group pricing advantages are gone?
Not necessarily. The gap between shoulder-season and peak-season pricing is likely to still exist, but it may be narrower than in previous years, and the window in which it is easiest to capture may be shorter. Availability should be checked programme by programme.
Why does St Patrick's week need separate contracting logic?
Because it tends to behave like peak season regardless of the calendar month around it — accommodation rates, parade-route traffic restrictions and advance-booking pressure resemble summer more than a typical March week.
Is west-coast Ireland on the same demand curve as Dublin?
Not necessarily. Dublin tends to absorb national demand growth most directly; the west coast runs on a smaller accommodation and coach base with its own seasonal pattern, which needs its own lead time regardless of what Dublin is doing.
What source backs the Q1 growth figures?
Ireland's Central Statistics Office (CSO), as reported in the Tourism Ireland release for January to March 2026. The Q1 share of annual spend is stated in the same release.
Does this change when Irish group programmes should be contracted?
It strengthens the case for contracting shoulder-season Irish programmes early rather than waiting for a confirmed group size. Lead times vary by supplier and are agreed programme by programme.
Building a group programme in Ireland?
BRACAP has operated ground product across Europe since 2007. Send us your dates, the regions you are covering and your group size, and we can review where the shoulder-season advantage still looks workable and where it may be tightening. See the destinations we operate across Europe, or send us your programme and we can review it.